

Live Spot Gold
Bid/Ask
3,747.603,749.60
Low/High
3,734.403,858.30
Change
-100.60-2.61%
30daychg
-416.50-10.00%
1yearchg
-296.90-7.34%
Live Gold Spot Prices & Market News
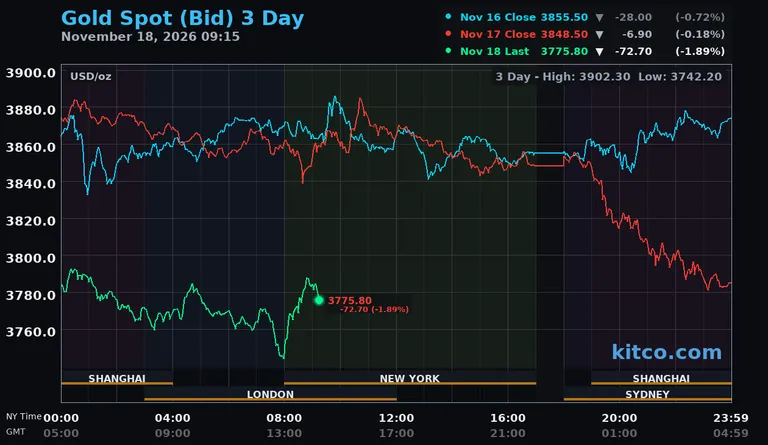
(Kitco NewsWire, Wed. Nov. 18th, 2026) – Spot gold and silver prices were sharply lower in early U.S. trading Wednesday, as expectations for additional Federal Reserve interest rate increases and a firm U.S. dollar continued to pressure precious metals despite escalating military tensions in the Persian Gulf. Gold fell to its lowest level since September 2025, breaking below the $3,800.00 level, while silver suffered heavier losses amid broad commodity selling and concerns about industrial demand. Spot gold was trading near $3,777.00 an ounce, down $71.50, or 1.86%, while silver was trading near $45.650 an ounce, down $1.619, or 3.42%. Gold had traded as low as $3,742.20 during the session, while silver touched $45.060.
Wednesday morning’s U.S. economic data presented a mixed picture of the housing market, with stronger construction activity offset by a sharp decline in building permits and weaker mortgage demand. October housing starts increased 9.9% to a seasonally adjusted annual rate of 1.309 million units, exceeding expectations for 1.25 million and recovering from September’s decline. However, building permits fell 7.4% to 1.295 million units, substantially below expectations for 1.38 million, suggesting weaker residential construction activity ahead. The combination of weaker forward-looking housing indicators, slowing industrial activity and continued price pressures complicates the Federal Reserve’s policy outlook. Softer growth could support Treasury bonds and gold, although persistent inflation and expectations for additional interest rate increases remain significant headwinds for precious metals.
Market positioning remains heavily tilted toward another Federal Reserve interest rate increase at the Dec. 8-9 meeting, with the latest published futures assessment indicating a 95.7% probability of a 25-basis-point increase and a 4.3% probability of a 50-basis-point move. Recent hawkish commentary from Federal Reserve officials has reinforced expectations that borrowing costs will remain elevated as policymakers attempt to contain inflation. The dollar index strengthened toward 103.70, near its highest level in 19 months, while the benchmark 10-year Treasury yield remained near the 5.1% area. Investors are focused on Wednesday’s October pending home sales at 10 a.m. EST and the minutes from the Fed’s Oct. 27-28 meeting at 2 p.m. EST. The minutes could clarify policymakers’ concerns about persistent inflation and the likelihood of additional tightening. More hawkish commentary could reinforce dollar strength and pressure gold, while signs of concern about slowing economic activity could moderate Treasury yields and provide some support to bullion.
Crude oil prices declined Wednesday as evidence of rising U.S. petroleum inventories and expectations for increasing global supply offset concerns about renewed disruptions to Persian Gulf shipping. Brent crude futures were trading near $91.99 a barrel, down approximately 1.23%, while Nymex WTI crude was near $84.34, down 1.94%. Preliminary industry figures indicated that U.S. crude inventories increased by approximately 5.28 million barrels during the week ended Nov. 13, while gasoline stocks rose 5.12 million barrels. The inventory increases reinforced expectations for a global petroleum surplus as Middle Eastern exports recover. The official weekly U.S. petroleum inventories report is scheduled for 10:30 a.m. EST. Lower crude prices could help moderate energy-driven inflation, although persistent underlying U.S. price pressure remains the more immediate concern for Federal Reserve policy.
Global equity markets were mixed Wednesday as stronger-than-expected Nvidia earnings helped stabilize technology shares following Tuesday’s broad international selloff. The previous U.S. session saw the Dow Jones Industrial Average decline 1.64%, the S&P 500 lose 1.03% and the Nasdaq Composite fall 0.74%, while Canada’s S&P/TSX Composite declined 1.14%. European markets also suffered substantial losses Tuesday, with the Stoxx 600 falling 1.75%, Germany’s DAX declining 2.08% and the U.K.’s FTSE 100 retreating 1.76%. Wednesday’s European trading was comparatively steady, with gains in selected technology shares offsetting continued weakness in mining companies as precious and industrial metals declined. Asian markets were mixed, while U.S. stock index futures pointed to a firmer opening following Nvidia’s results. The recovery in technology sentiment offered some relief to equities, but continued weakness in commodities indicated that investors remained concerned about restrictive monetary policy and the outlook for global demand.
The key outside markets see Nymex WTI crude oil futures lower and trading around $84.34 a barrel, while Brent crude was near $91.99. The U.S. dollar index was firmer near 103.70, maintaining pressure on precious metals, while the benchmark 10-year U.S. Treasury yield remained near the 5.1% area. Expectations for another Federal Reserve rate increase in December continued to limit confidence in a sustained recovery in gold and silver, despite renewed geopolitical uncertainty. (Kitco Global Index shows how much of today’s gold move is the dollar versus the gold market itself.)
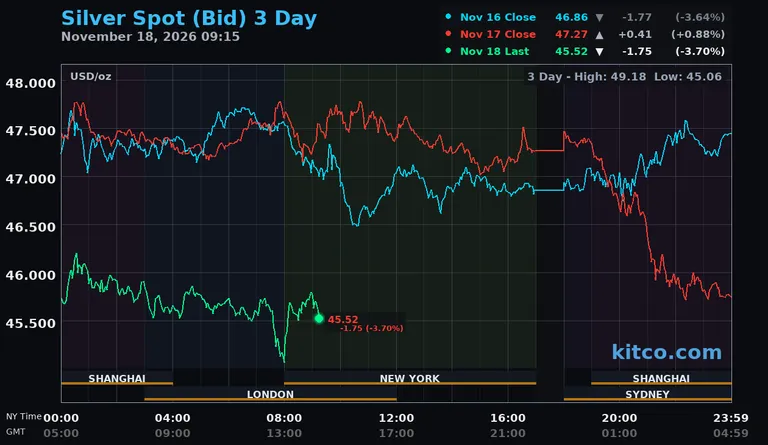
Spot silver bulls’ next upside price objective is to drive prices back above the $46.590 to $46.860 resistance zone, with a sustained move through the upper boundary needed to strengthen the recovery. The next downside price objective for the bears is a break below $45.740, with a deeper downside target at $45.540. First resistance is seen at $46.590 and then at $46.860. Next support is seen at $45.740 and then at $45.540.
Posted by:
Jack Dempsey, President
401 Gold Consultants LLC
jdemp2003@gmail.com